
Impôts ici
International Taxation in Montreal
International taxation affects all situations where income, assets, a business, or tax residency crosses Canadian borders. Are you arriving in Canada, leaving the country, holding assets abroad, receiving Canadian-source income as a non-resident, or developing business activities outside Canada?
These situations require rigorous analysis, as tax obligations can vary depending on residency status, type of income, the country involved, and applicable tax treaties.
Impôts ici assists individuals, entrepreneurs, investors, and corporations with their international tax processes. Our role is to clarify your obligations, prevent filing errors, coordinate necessary forms, and guide you towards a compliant, effective strategy tailored to your situation.
Find the right international tax subtopic. For mobility matters, start with tax residency and international mobility, Canadian expatriates, foreign workers in Canada, international students, or retirees abroad.
For income, assets, and filings, see tax returns for non-residents, foreign assets and income reporting, foreign investments in Canada, sale of property by a non-resident, and T2 declarations for non-resident corporations.
For structure and compliance issues, consult international tax treaties, international business transfer, international estate planning, voluntary disclosure of foreign assets, international tax audits, and the guide to international tax forms.
Your projects require professionals to assist you ...
International Taxation
A taxation that primarily depends on your status
Before even discussing income, taxes, or forms, it is essential to establish your tax status. A person can be a resident, non-resident, deemed resident, or factual resident based on their ties to Canada. The place where you live is not always sufficient to determine this.
Family residency, assets retained in the country, bank accounts, professional activities, duration of stay, and personal ties can influence the analysis.
This step is crucial for newcomers, Canadians leaving the country, expatriates, retirees abroad, and mobile workers. An incorrect tax status can lead to incomplete filings, double taxation, misapplied withholdings, or avoidable penalties.
International Taxation
Different obligations depending on income and assets
In international taxation, each income must be examined according to its source and tax treatment. Canadian rental income from a non-resident, pensions, dividends, employment income, capital gains, foreign income of a Canadian resident, and distributions from foreign retirement plans are not treated the same way.
Assets held abroad add another layer of complexity. Certain accounts, investments, properties, interests in foreign companies, or trusts may need to be reported in Canada. Forms T1135, T1134, T1141, T1161, T1243, or T2062 do not apply to the same situations. A prior analysis allows for determining what needs to be filed, by when, and with what supporting information.
International Taxation
Non-residents, investors, and property owners in Canada
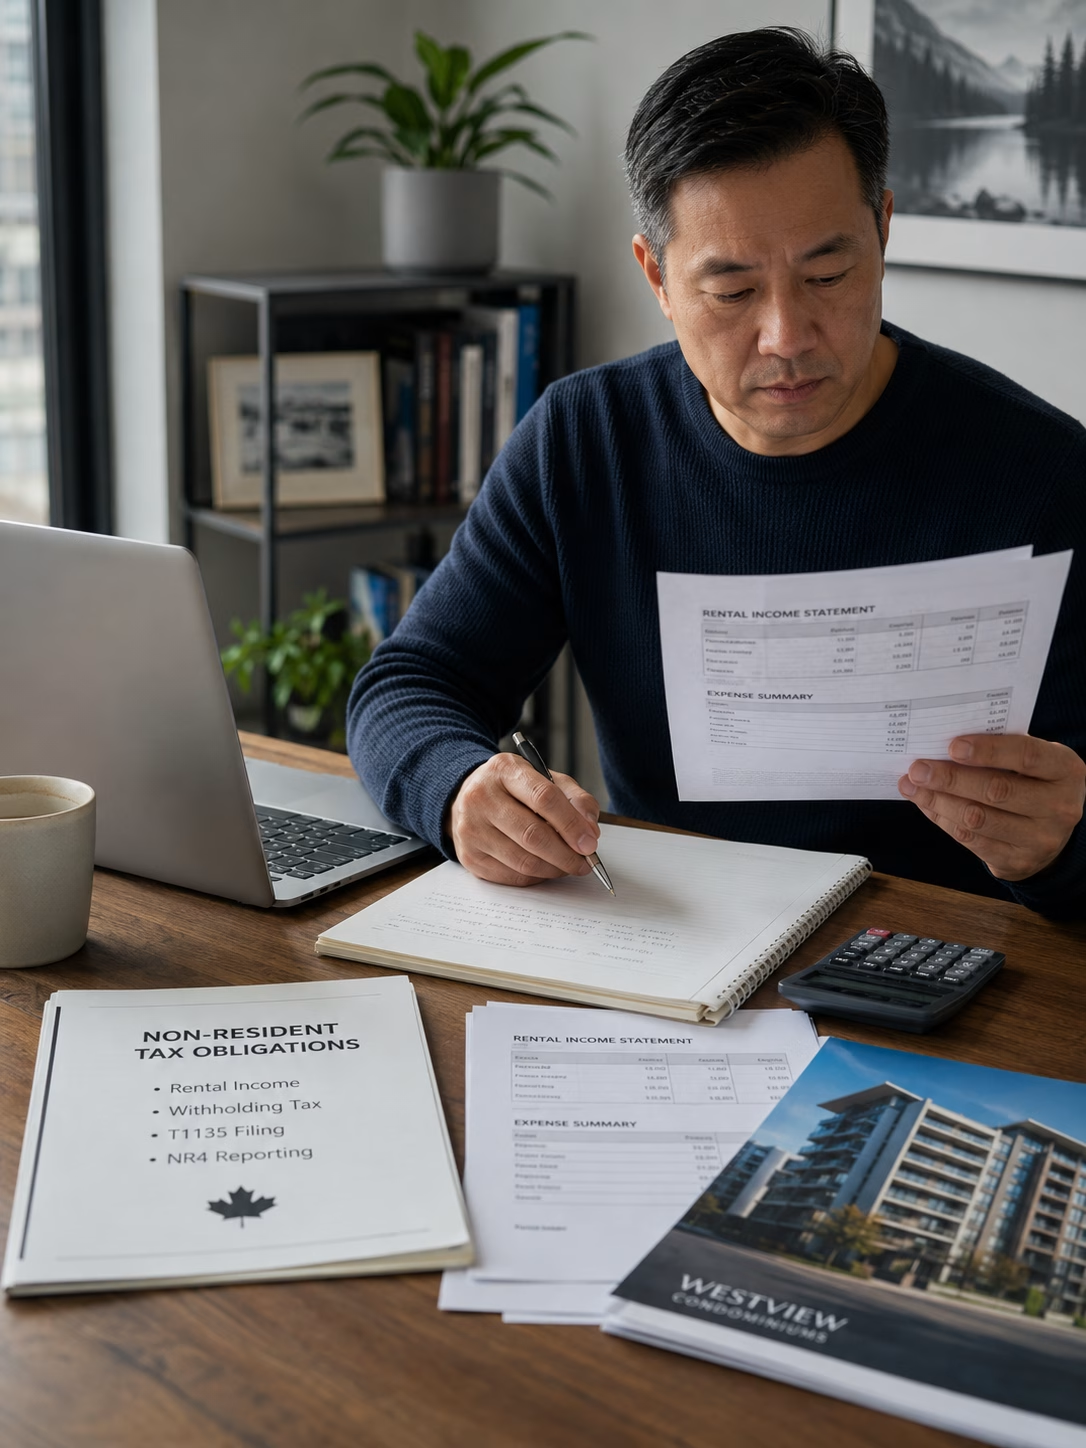
Non-residents of Canada may have tax obligations even if they no longer live in the country. Renting out a Canadian property, receiving a pension, selling real estate, operating a business, or realizing a taxable gain can trigger withholdings, filings, or requests for certificates.
The sale of a property by a non-resident is one of the most sensitive cases. The compliance certificate, forms T2062 or T2062A, filing deadlines, and withholdings must be planned before the transaction. Foreign investors must also consider the holding structure, financing, future exit tax, and tax treaties that may influence the outcome.
International Taxation
Businesses and cross-border issues
A non-resident business operating in Canada may need to file a T2 return, even if it believes its profits are protected by a tax treaty. The presence of a permanent establishment, services rendered in Canada, withholdings on payments, transactions with related parties, and capital movements must be examined closely.
Canadian businesses expanding internationally must also anticipate foreign income, tax credits, subsidiaries, share transfers, restructurings, and compliance obligations. Poorly structured international growth can create unexpected tax costs and complicate a future sale or transfer.
International Taxation
Preventing errors and regularizing past situations
Errors in international taxation are common: undeclared foreign assets, forgotten accounts, late-filed forms, improperly treated foreign income, misassessed residency status, or incorrectly applied tax treaties.
These errors can become significant when tax authorities obtain information through automatic exchange or during an audit.
Impôts ici can assist you in analyzing a past situation, preparing a voluntary disclosure, responding to a request from the Canada Revenue Agency or Revenu Québec, and correcting affected filings. The goal is to handle the case methodically, limit risks, and restore sustainable tax compliance.
Satisfied clients
Hours of experience
In tax savings
Years of experience serving you.
Discover us!
International tax support in Montreal
International taxation requires more than just a simple filing. It demands a comprehensive understanding of your personal, professional, and asset situation. Impôts ici helps you determine your obligations, choose the right forms, assess double taxation risks, and structure your processes with rigor.
Whether you are a Canadian resident with foreign income, a non-resident with assets in Canada, an international entrepreneur, a foreign student, a retiree abroad, or a non-resident corporation, our firm supports you in making the right tax decisions and avoiding unpleasant surprises.
Before filing or modifying a return, it is advisable to gather residency dates, concerned countries, received income, held assets, taxes paid abroad, and forms already submitted. This preparation allows for a quick assessment of priorities: immediate compliance, future optimization, correction of past years, or planning before a transaction. Impôts ici can thus intervene with a complete view rather than from a single isolated form.