
Impôts ici
Retirees Abroad
International retirement raises many tax questions. A Canadian who moves abroad may continue to receive pensions, RRSP or RRIF withdrawals, government benefits, Canadian investment income, or rental income. A foreign retiree arriving in Canada may also retain retirement plans from their home country, such as a 401(k), IRA, or Roth IRA in the United States.
Each income must be analyzed according to tax residency, applicable treaties, and withholding taxes.
Impôts ici assists retirees, pre-retirees, and cross-border families in the tax planning of their retirement income. Our team helps you avoid double taxation and structure your filings accurately.
Your business requires professionals to support you
Retirees Abroad
Determining Tax Residency in Retirement
A retiree leaving Canada does not automatically become a non-resident for tax purposes. Ties retained in Canada, such as a residence, spouse, accounts, property, provincial coverage, or economic interests, can influence the analysis. The country of residence may also claim tax residency.
Tax residency determines the income to be reported in Canada. A Canadian resident generally reports their worldwide income. A non-resident reports certain Canadian-source income, often subject to withholding. Tax treaties can clarify situations where two countries consider the same person a resident.
Retirees Abroad
RRSP, RRIF, Pensions, and Withholding Taxes
Withdrawals from RRSPs, RRIFs, and other Canadian plans paid to a non-resident may be subject to withholding taxes. The applicable rate may depend on the nature of the payment and the tax treaty between Canada and the country of residence.
In some cases, a declaration under Section 217 may be considered to determine if the final treatment is more advantageous.
It is important to plan withdrawals before departure or before a change of country. Large withdrawals, plan conversions, and periodic payments do not always have the same consequences. Impôts ici can help you compare scenarios.
Foreign Plans: 401(k), IRA, and Roth IRA
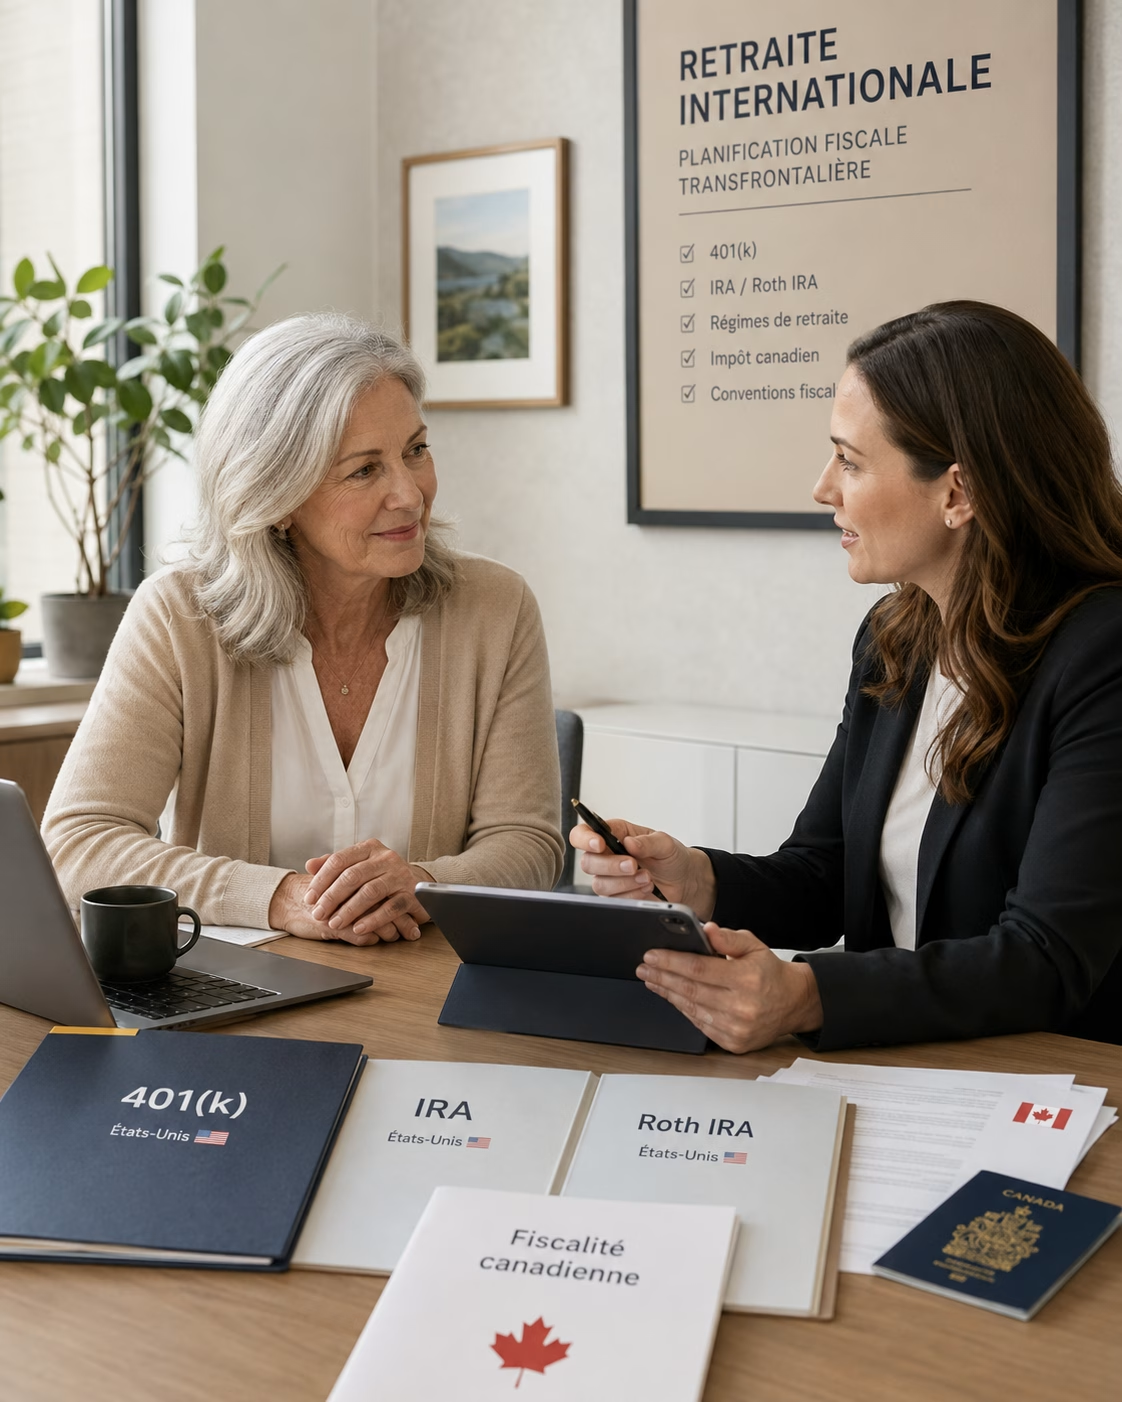
U.S. retirement plans add particular complexity for individuals who become Canadian residents or return to Canada after a career in the United States. Distributions from 401(k), IRA, or Roth IRA must be analyzed according to Canadian rules and the Canada-U.S. tax treaty.
The Roth IRA requires special attention, as certain elections or actions may be necessary to preserve favorable tax treatment in Canada. Transfers, conversions, early withdrawals, and mandatory distributions must be evaluated before taking action. A decision made in the United States may have unexpected Canadian consequences.
Foreign Pensions and Tax Credits
A Canadian resident receiving a foreign pension may need to report it in Canada. If withholding has been applied in the foreign country, a foreign tax credit may sometimes reduce double taxation. Some tax treaties may also provide for partial exemptions or special treatment.
Foreign documents are not always easy to integrate into a Canadian tax return. Amounts must be converted, taxes actually paid must be distinguished from social contributions, and the taxable period must be correctly identified. Impôts ici can help you organize this information.
Satisfied Clients
Hours of Experience
In Tax Savings
Retirees Abroad
Estate Planning, Heirs, and International Wealth
Retirement abroad must also be coordinated with estate planning. Retirement plans, properties, foreign accounts, non-resident beneficiaries, and heirs living in multiple countries can create significant tax issues.
The treatment upon death may vary between Canada and the foreign country.
Proactive planning allows for the documentation of beneficiaries, values, withdrawal rules, withholdings, and the effects of tax treaties. It also helps prevent heirs from discovering complex tax obligations after death.
Retirees Abroad
Support for a Tax-Secure Retirement
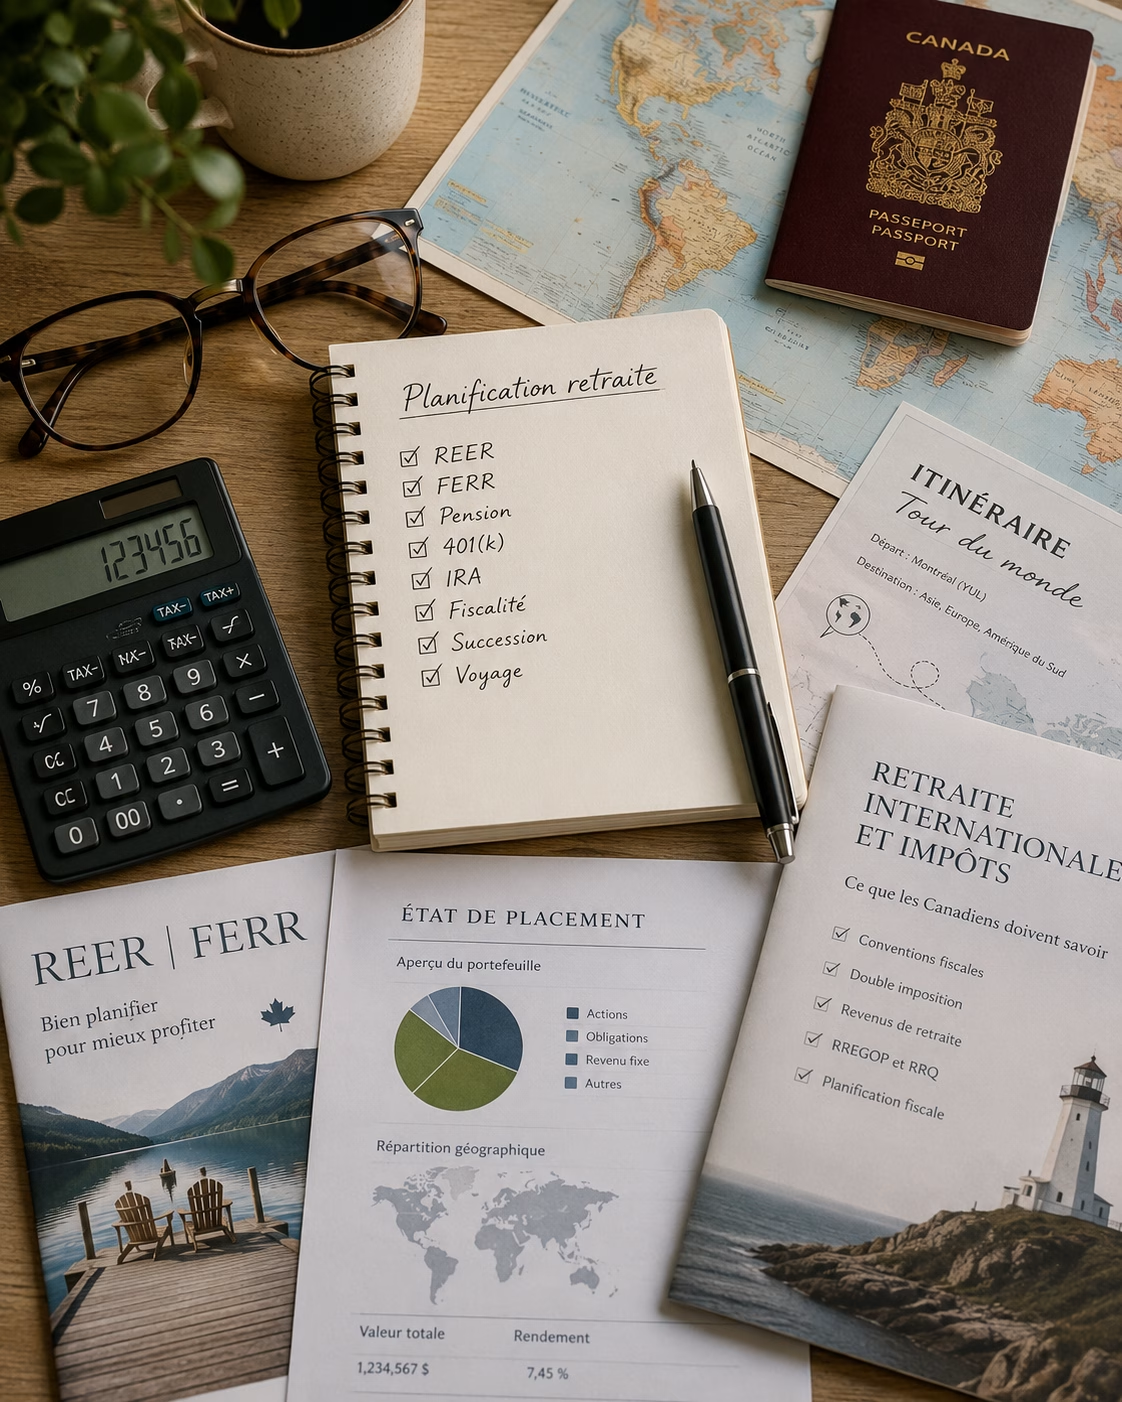
The taxation of retirees abroad requires a comprehensive view of income, plans, and the countries involved. Impôts ici supports you in determining your status, analyzing your pensions, planning your withdrawals, coordinating tax credits, and preparing your returns.
Whether you live abroad, return to Canada, or hold U.S. plans like a 401(k), IRA, or Roth IRA, our firm helps you protect your retirement income and avoid unpleasant tax surprises.
Before making a decision regarding withdrawals, transfers, or changes of country, it is advisable to prepare statements of plans, countries of residence, expected amounts, withholdings already applied, relevant tax treaties, and documents from foreign plans. Decisions regarding an RRSP, RRIF, 401(k), IRA, or Roth IRA should not be made solely based on the rules of the country where the account is located.
Impôts ici
A Company Close to You, Here to Help!
Years of Experience Serving You.
Discover Us!
Retirees Abroad with Impôts ici
Impôts ici can compare scenarios of gradual withdrawal, one-time withdrawal, deferral, staying abroad, or returning to Canada. This analysis helps protect available income and avoid unexpected taxation at the wrong time.
Planning must also consider currency fluctuations and the cost of living in the chosen country. The gross amount of a pension does not always reflect the income actually available after withholdings, foreign taxes, credits, bank fees, and conversion. An annual tax projection helps avoid decisions made based on theoretical income.