
Regularize the file before acting on estimates
Voluntary disclosure of foreign assets and income
Was a foreign account, property, corporation, trust or income item omitted from a return? The first response should not be to send an approximate number. The affected years, taxable income, missing information returns and any action already taken by the tax authorities must be identified.
Impôts Ici assists taxpayers who need to correct an international matter. We reconstruct the file, compare the available correction routes and prepare the information required for the applicable federal or Quebec program. Relief is never automatic, and the underlying tax remains payable.
An effective correction begins with a complete chronology
Undeclared foreign assets
A voluntary disclosure is more than an amended return
Voluntary disclosure programs may, in certain circumstances, allow omissions to be corrected before they are discovered through an audit or enforcement action. Eligibility, the degree of relief and the required records depend on the facts and the program rules in effect when the application is made.
The review must determine whether the authority has already contacted the taxpayer or a related person, whether the correction is complete and whether the years and amounts can be supported. An incomplete or inconsistent request can complicate regularization. The Canada Revenue Agency and Revenu Québec processes are separate and must be coordinated.
International voluntary disclosure
Which assets, income and forms may be involved?
Common omissions include interest, dividends, rent, pensions, gains, bank accounts, investments, real estate or interests in foreign entities. Forms T1135, T1134, T1141 or T1142 may apply in addition to income tax. See foreign property and income reporting to distinguish these obligations.
A fund transfer, inheritance, loan or proceeds from selling property is not automatically income. The legal and economic nature of each amount must be identified and foreign statements reconciled with Canadian returns. This step prevents both over-correction and under-reporting.
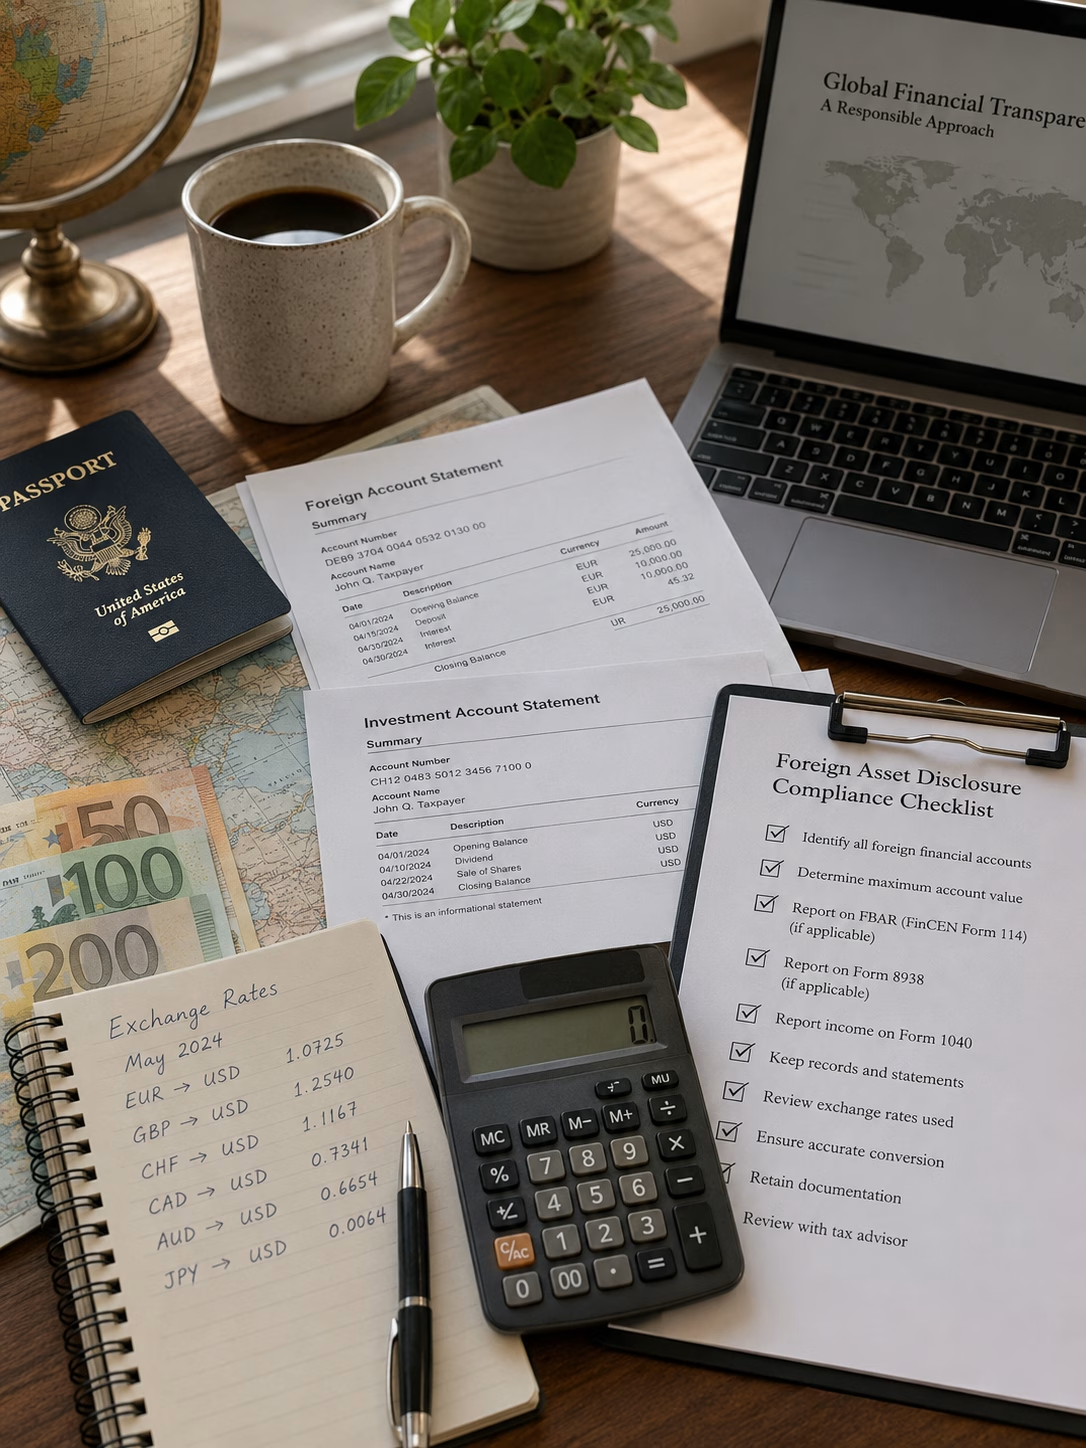
Assess the risk before communicating
The file should answer concrete questions: how many years are affected? Which records still exist? Did a foreign financial institution report information? Has a request, audit or assessment already started? Was a related person contacted?
Depending on the answers, the proper route may be a voluntary disclosure, adjustment request, late return or audit response. When the authorities have already taken steps, review international tax audit or tax representation services instead.
Reconstruct and document the affected years
Preparation may include bank statements, corporate records, contracts, property deeds, foreign returns, proof of tax paid, exchange-rate history and income calculations. Amounts must be assigned to the correct year and taxpayer.
The missing forms are then prepared consistently with the corrected returns. The guide to international tax forms explains their general functions, but the appropriate filing depends on the actual structure and facts.
Satisfied Clients
Hours of Experience
In Tax Savings
Undeclared foreign assets
After correction: organize future compliance
Sustainable regularization includes an asset inventory, filing calendar, conversion method, record-retention process and coordination with advisers in the foreign country. Income must still be tracked in years when no separate information return is required.
This organization is particularly important for families inheriting property, entrepreneurs holding a foreign corporation and investors using several institutions. It reduces the risk that the omission will recur simply because records arrive in another language or at a different time.
International voluntary disclosure
Discreet, methodical and realistic support
We review the chronology, amounts, forms and communications already received before recommending a route. The engagement may also require coordination with a lawyer or a professional in the foreign country when the character of an amount or structure is uncertain.
The objective is not to promise an outcome, but to present a complete, coherent and verifiable file and update current obligations. Interest, penalties and possible relief are evaluated under the rules and decisions applicable to the case.
Impôts Ici
A fully remote service
Years of Experience Serving You.
Disclosure of foreign assets
Regain control before the file becomes heavier
Prepare a list of countries, accounts, property, entities, income, years and communications received. Do not amend several returns separately before establishing the full picture: the same fact may affect income, foreign tax credits and more than one information return.
To have the possible approach reviewed, contact Impôts Ici. Records can be examined remotely and organized before anything is sent to the authorities.