
Impôts ici
International Tax Audits
International tax audits are becoming increasingly common, especially when foreign accounts, income, or assets appear in the information provided to tax authorities. Canada participates in automatic information exchange mechanisms, allowing the Canada Revenue Agency to obtain data from foreign financial institutions.
An omission that once went unnoticed can now be detected more easily.
Impôts ici assists taxpayers targeted by a request for information, an audit, or a regularization related to foreign assets. Our team helps you respond methodically, accurately, and cautiously.
Your business needs professionals to support you
International Tax Audits and Automatic Exchanges
Understanding Automatic Information Exchanges
The Common Reporting Standard, often referred to as CRS, enables the automatic exchange of financial information between participating tax administrations. Financial institutions can transmit information about certain accounts held by non-residents, such as the account holder’s identity, country of tax residence, account balance, and certain income.
This information does not replace a full audit but can trigger questions.
If a foreign account appears in the data received and no T1135 form or foreign income has been reported, the CRA may request explanations or open an audit file.
International Tax Audits and Automatic Exchanges
Common Requests from Tax Authorities
An international audit may focus on bank accounts, investments, foreign properties, non-resident corporations, trusts, rental income, dividends, interest, capital gains, or pensions. Authorities may request statements, contracts, foreign declarations, proof of taxes paid, ownership documents, or explanations regarding the source of funds.
It is important not to respond too quickly with incomplete information. An inaccurate response can create new questions or give the impression that the case is not well managed. Impôts ici helps you organize the facts before communicating with the authorities.
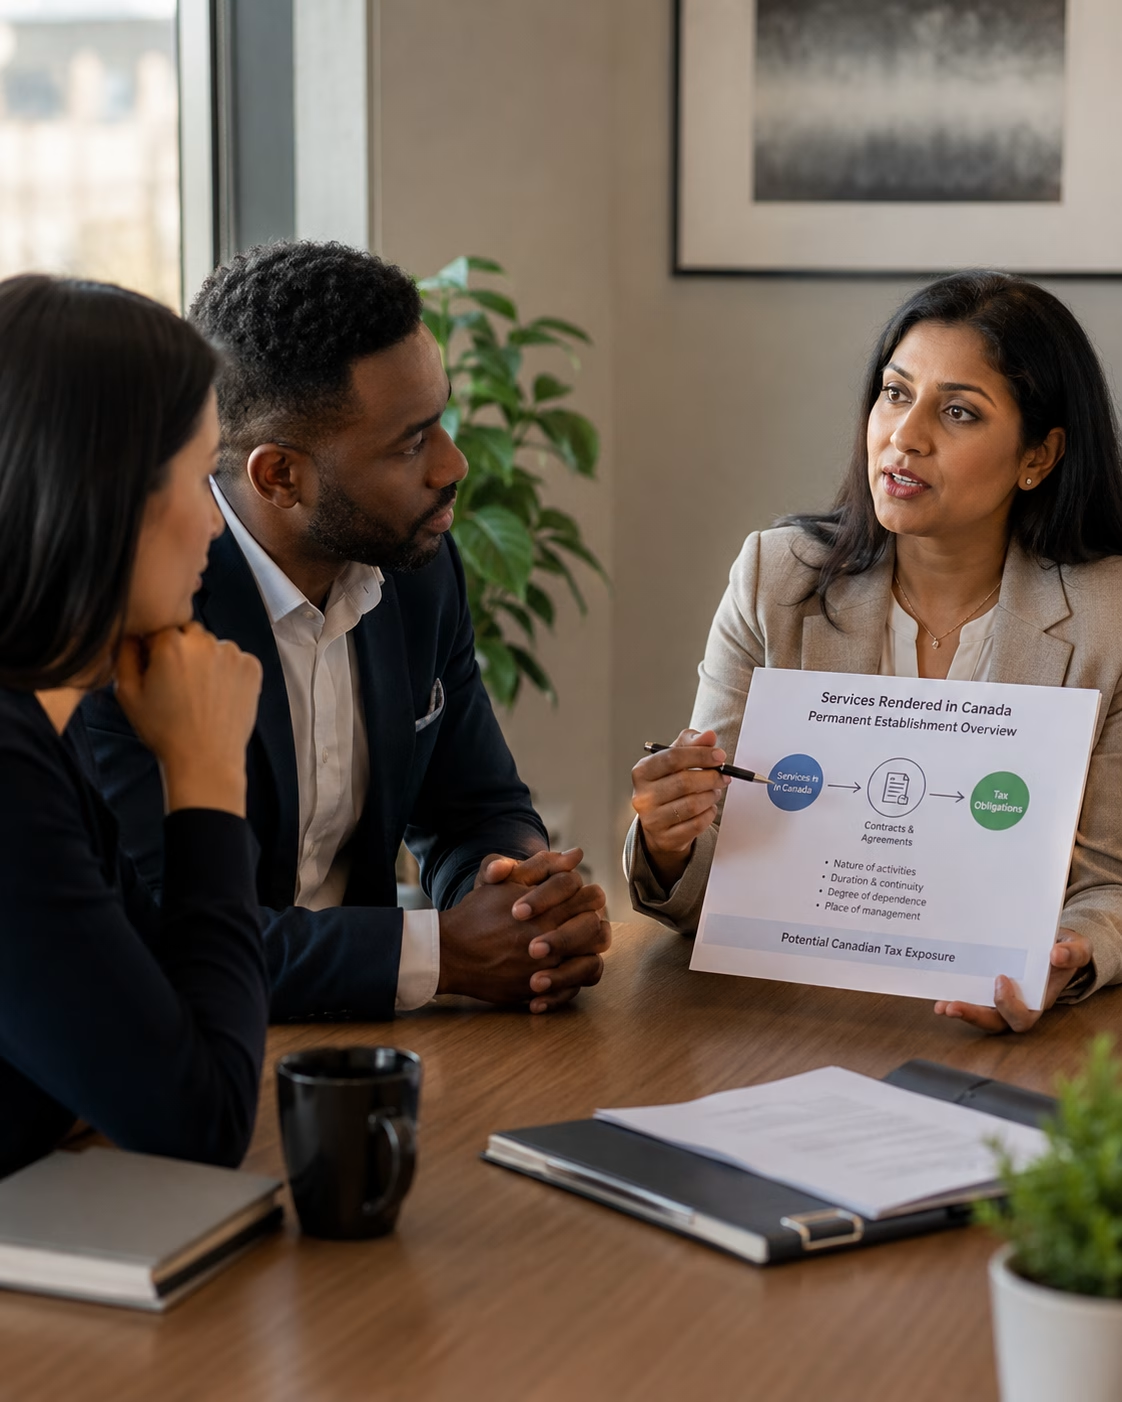
T1135, T1134, and Unfiled Forms
Foreign information forms are often at the heart of audits. The T1135 targets certain foreign assets held by Canadian taxpayers. The T1134 pertains to foreign affiliated corporations. Other forms may apply to trusts, transfers, or specific situations.
An omission of a form can lead to penalties even if the tax owed is low. Therefore, it is essential to verify not only the reported income but also the information reporting obligations. An international audit requires a comprehensive review of the affected years.
Audit or Voluntary Disclosure?
When an error is discovered, the strategy depends on timing. If authorities have already begun an audit or communicated about the omission, voluntary disclosure may no longer be available for the targeted items. A solid audit response must then be prepared.
If no official action has yet begun, voluntary disclosure may sometimes be considered. Impôts ici helps you determine the most appropriate course based on the facts, dates, available documents, and risks.
Satisfied Clients
Hours of Experience
Tax Savings
International Tax Audits and Automatic Exchanges
Preparing a Defensible Response
A response to an audit must be clear, complete, and consistent. It is necessary to reconstruct amounts, convert currencies, distinguish between capital and income, identify foreign taxes paid, explain transfers, and provide relevant evidence.
A structured approach reduces the risk of misunderstandings.
The taxpayer should also avoid submitting documents without analysis. Some statements may contain information that requires explanation, such as family transfers, asset sales, inheritances, loans, or movements between accounts. Each element must be placed in its tax context.
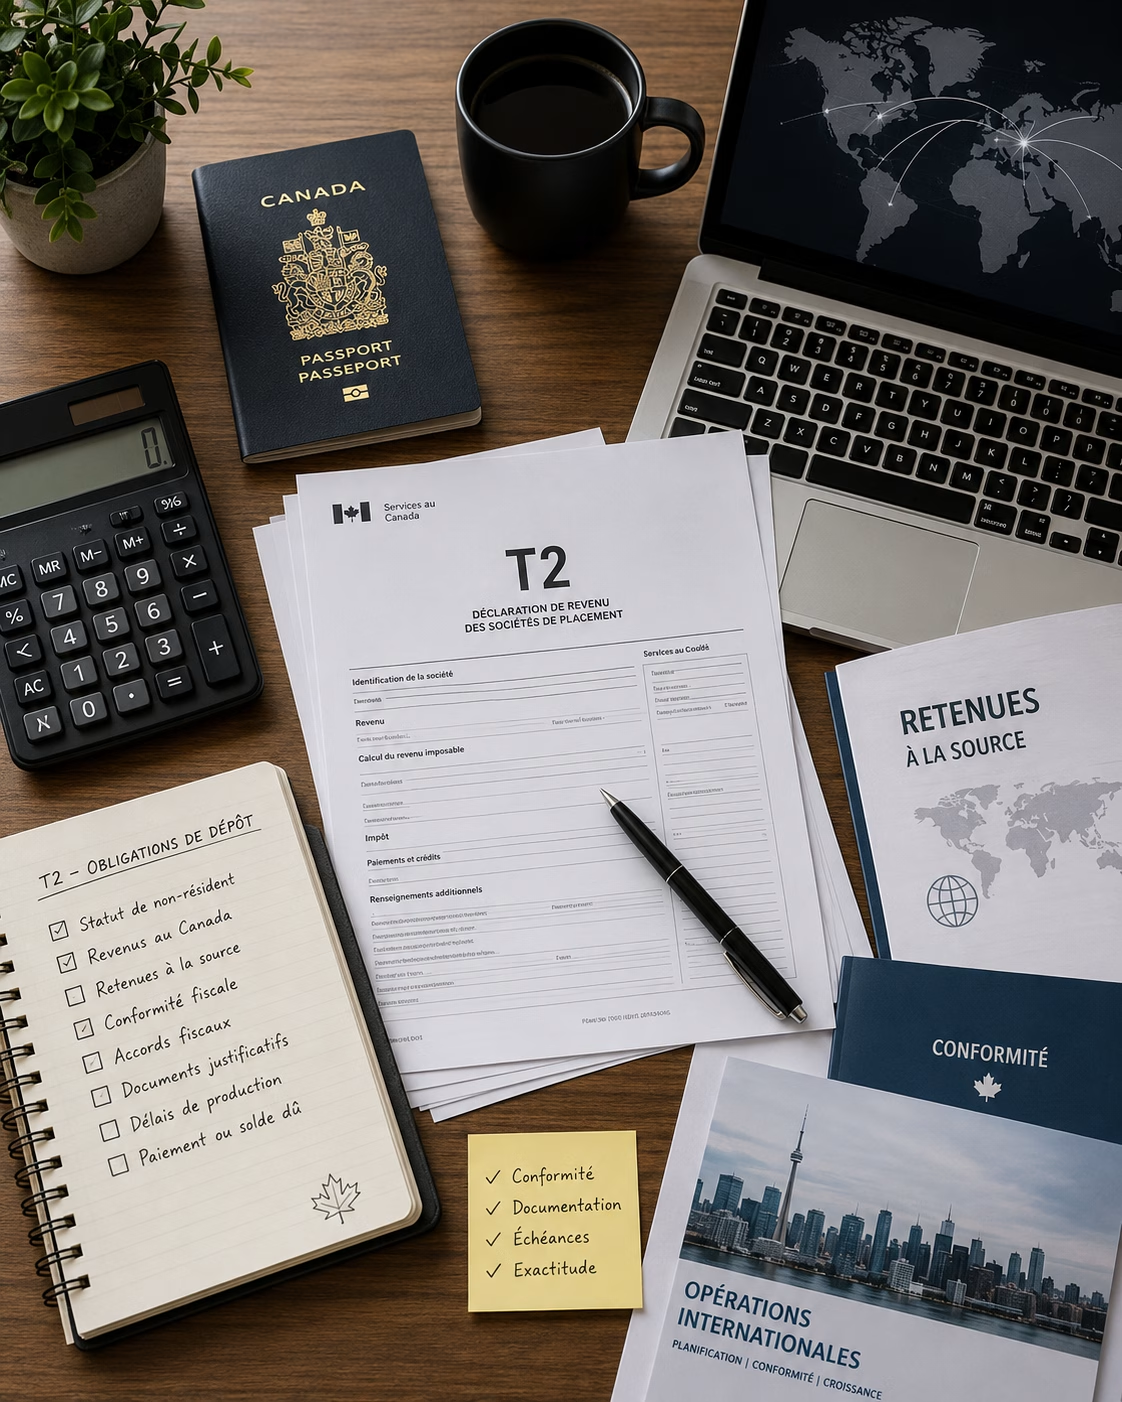
International Tax Audits and Automatic Exchanges
Support in International Tax Representation
Impôts ici supports you in international tax audits, whether they come from the CRA, Revenu Québec, or an information exchange. Our team analyzes requests, prepares responses, gathers evidence, and helps you defend your position.
If you have received a letter regarding foreign accounts, international income, a T1135, or a foreign corporation, our firm can intervene quickly to structure the case and limit tax risks.
Upon receiving a letter, it is advisable to note deadlines, the years involved, requested documents, and mentioned subjects. You should then gather foreign statements, declarations, proof of taxes paid, ownership documents, and explanations regarding the source of funds. A partial or improvised response can prolong the audit.
Impôts ici
A company close to you, to help you!
Years of experience serving you.
Discover us!
The International Tax Audits and Automatic Exchanges with Impôts ici
Impôts ici can act as a coordination point to prepare the response, organize the documents, and limit irrelevant information. The goal is to respond completely to the request without creating confusion or unnecessary inconsistencies.
When the audit spans multiple years, it is also necessary to reconstruct the evolution of assets. A balance of a foreign account may come from old capital, an inheritance, a sale, previously declared income, or a transfer between accounts. Without a timeline, these movements can be misinterpreted. Impôts ici helps you place each amount in its tax context and distinguish taxable income from mere asset movements.
An international audit can also have provincial repercussions. When the taxpayer is in Quebec or the asset in question is Quebec-based, responses must be consistent with Revenu Québec and the CRA.
This consistency becomes essential when multiple tax years are open simultaneously.