
Impôts ici
International Business Transfer
Transferring a business becomes more complex when a buyer, shareholder, heir, related company, or part of the business is located abroad. Share sales, asset sales, family succession, intergenerational transfers, corporate reorganizations, or international expansions can trigger tax consequences in Canada and another jurisdiction.
Insufficient planning can reduce the net value actually retained by the seller.
Impôts ici supports entrepreneurs, shareholders, and executives considering a transaction or transfer with an international dimension. Our team helps you structure the transfer, anticipate taxes, and coordinate tax obligations related to the countries involved.
Your business requires professionals to support you
International Business Transfer
Identify the nature of the transfer
A business transfer can take several forms. It may involve a share sale to a foreign buyer, a sale of assets located in Canada, a transfer to a foreign company, a family succession with non-resident heirs, or a reorganization aimed at preparing for expansion outside Canada. Each of these options has different tax consequences.
The first step is to understand what is being transferred, to whom, for what value, and in what context. The tax treatment may vary depending on whether shares, assets, an operating business, an interest in a holding company, or intellectual property is being transferred. A preliminary analysis helps avoid decisions made solely based on commercial negotiation.
International Business Transfer
Plan for capital gains and Canadian tax
Transferring a business can generate a taxable capital gain. When foreign shareholders or buyers are involved, it is essential to examine whether Canada retains a right to tax, whether a tax treaty alters the outcome, and whether specific withholding or reporting requirements apply. The rules can be even more complex when the business holds real estate, shares of private companies, or other taxable Canadian assets.
Planning must also incorporate existing optimization opportunities in Canada, such as the capital gains exemption when conditions are met, corporate purification, prior corporate reorganization, or the choice between share sales and asset sales. In an international context, these options must be coordinated with foreign rules.
Family transfer with non-resident heirs
A family business may be intended for children, family members, or heirs living abroad. This situation raises issues of tax residency, control, future distribution, dividend withholding, governance, and succession.
The transfer must not only meet a family objective: it must also remain fiscally viable.
Non-resident heirs may receive Canadian shares or interests, but the consequences must be assessed before the transfer. Questions arise regarding the value of the business, financing the buyout, anti-avoidance rules, tax treaties, and future profit management.
Reorganization before sale or expansion
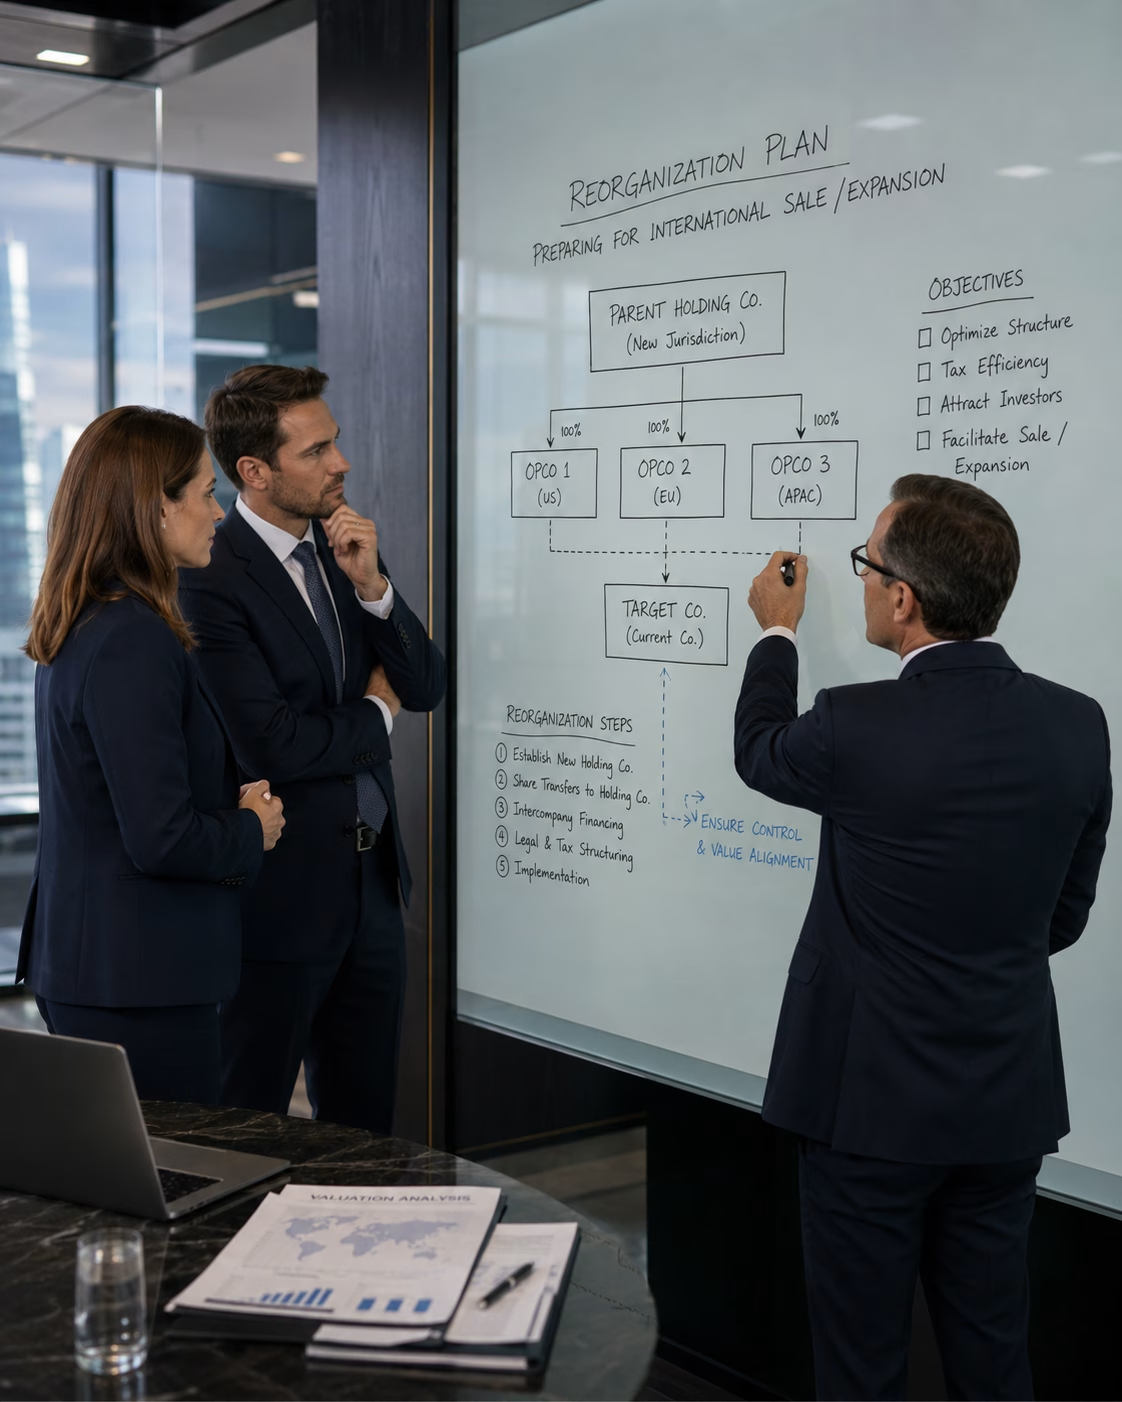
Before an international transaction, a corporate reorganization may be necessary. It may aim to isolate certain assets, separate activities, consolidate interests, establish a holding company, prepare for a merger, or facilitate the entry of a foreign investor.
These operations require precise coordination between taxation, accounting, and corporate law.
A poorly planned reorganization can create immediate tax liabilities, compromise an exemption, complicate due diligence, or raise concerns for the buyer. Impôts ici helps you evaluate available options and structure the approach before the transaction progresses too far.
Satisfied clients
Hours of experience
In tax savings
International Business Transfer
Tax treaties and double taxation
When a transfer involves two countries, the applicable tax treaty may influence the right to tax, the treatment of gains, withholdings, and tax credits. However, it does not replace domestic analysis. The treaty must be read in relation to Canadian laws, the residency of the parties, the nature of the transferred assets, and the structure of the transaction.
Double taxation may occur if both Canada and the other country consider they have the right to tax part of the gain. Serious planning allows for anticipating these overlaps and documenting the positions taken in each declaration.
International Business Transfer
A strategic support for transferring with confidence
The international transfer of a business requires a comprehensive view. Impôts ici assists you in analyzing the scenario, evaluating tax consequences, coordinating forms, preparing the reorganization, and communicating with other professionals involved.
Whether you are selling to a foreign buyer, preparing for an international family succession, or restructuring your business before expansion, our firm helps you preserve the value of your business and avoid tax risks that could jeopardize the transaction.
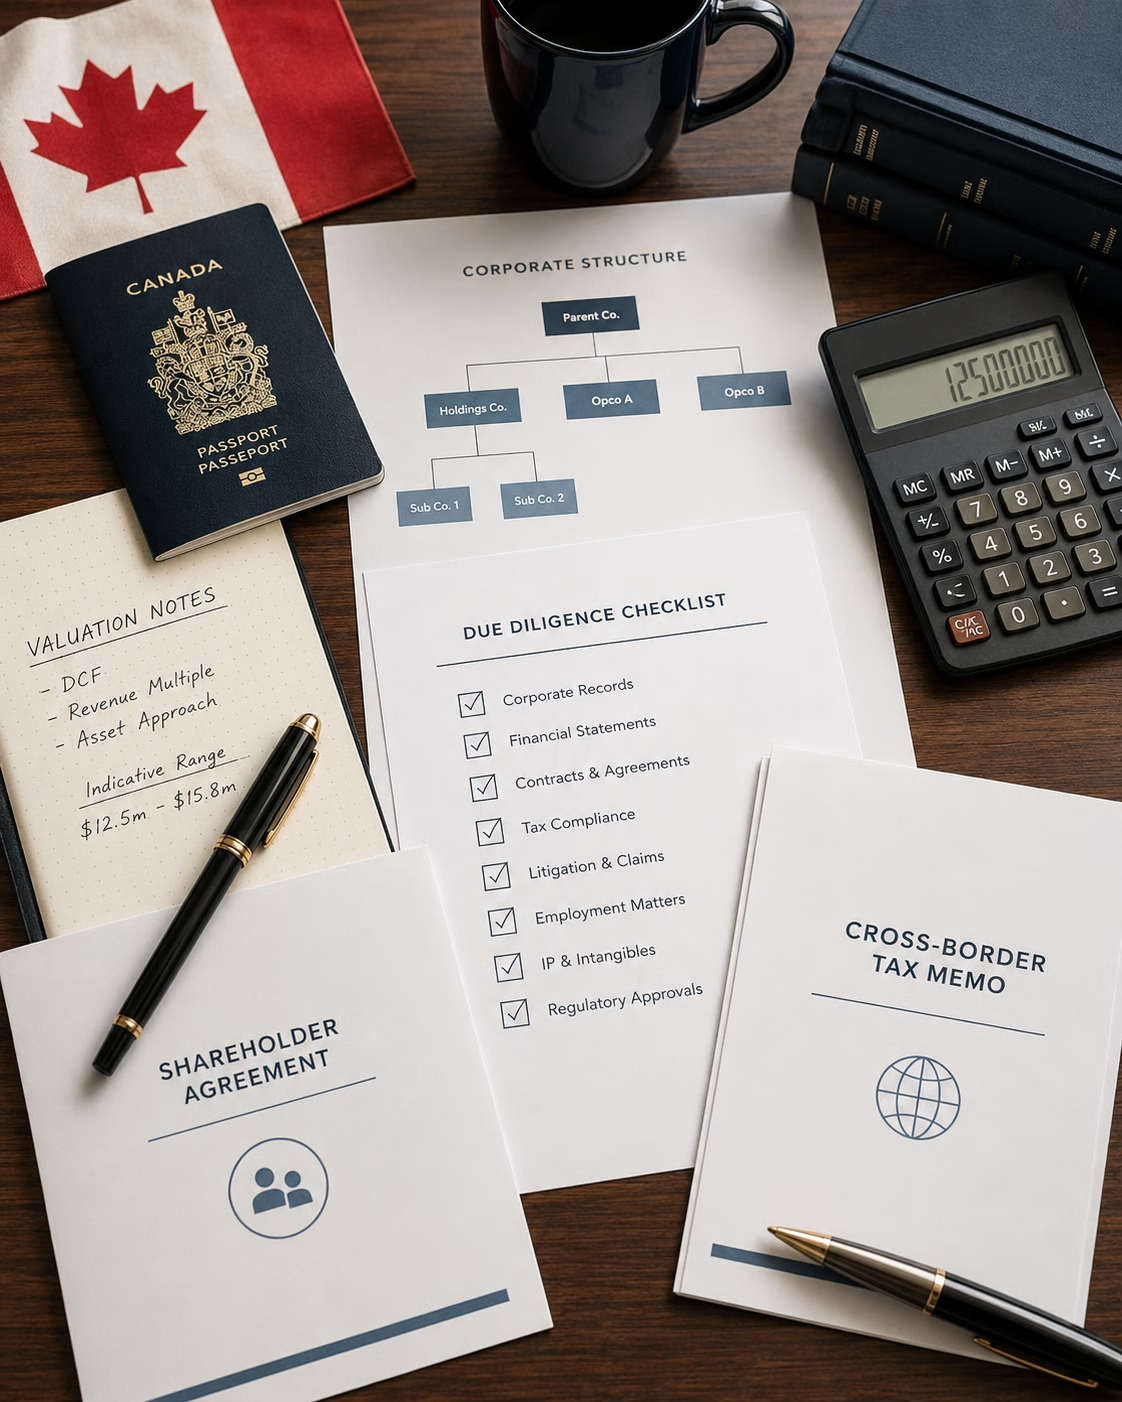
Before undertaking a transfer, it is advisable to prepare the corporate structure, financial statements, shareholder agreements, estimated business value, residency of the parties, held assets, and family or business objectives. This documentation helps distinguish compliance, optimization, and negotiation issues.
Impôts ici
A business near you, to help you!
Years of experience serving you.
Discover us!
The international business transfer with Impôts ici
Impôts ici can intervene early in the process to test various scenarios. An immediate sale, a freeze, a prior reorganization, or a gradual transfer do not yield the same tax result. In an international context, this comparison must be made before legal documents are finalized.