
Impôts ici
T2 Declaration for Non-Resident Corporations
A foreign corporation conducting business in Canada may be required to file a T2 return, even if it is not incorporated in the country. This obligation may apply when a non-resident corporation operates a business in Canada, owns taxable Canadian property, or realizes certain gains related to Canada.
Having a tax treaty does not automatically eliminate the obligation to file a return.
Impôts ici supports foreign corporations, international groups, non-resident entrepreneurs, and businesses developing Canadian activities. Our team helps you determine if a T2 is required and structure your tax compliance.
Your business needs professionals to support you
T2 Declaration for Non-Resident Corporations
When a Non-Resident Corporation Must File a T2
A non-resident corporation may be required to file a T2 return if it has carried on business in Canada during the year, realized a taxable capital gain, or disposed of taxable Canadian property.
This requirement may apply even when the corporation believes its profits are exempt in Canada under a tax treaty.
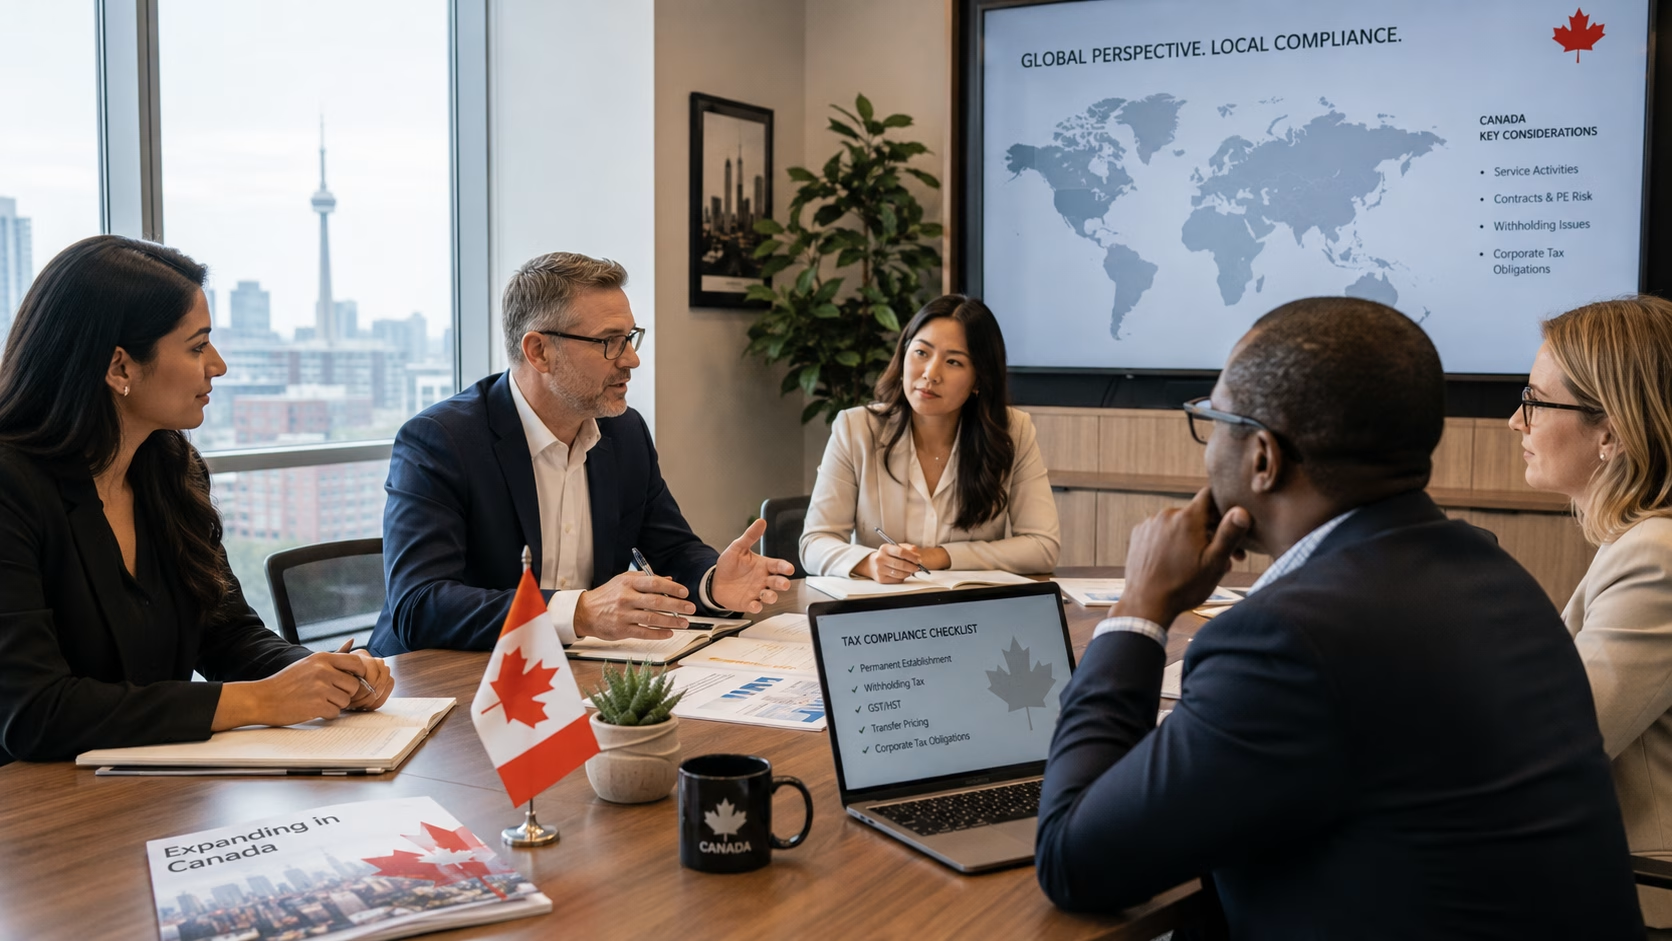
The challenge often lies in determining whether the activities conducted in Canada are sufficient to create an obligation. Sales, services, employees, agents, contractors, warehouses, sites, frequent travel, or contracts executed in Canada must be examined.
T2 Declaration for Non-Resident Corporations
Permanent Establishment and Tax Treaties
The concept of permanent establishment is central for foreign businesses. A tax treaty may limit Canadian taxation if the business does not have a permanent establishment in Canada. However, this analysis requires reading the applicable treaty and verifying the actual facts: office, fixed place of business, site, dependent agent, or prolonged presence.
Even when a business claims treaty protection, it may need to provide information to support its position. Certain schedules or information may be necessary to document the exemption claim based on a tax treaty.
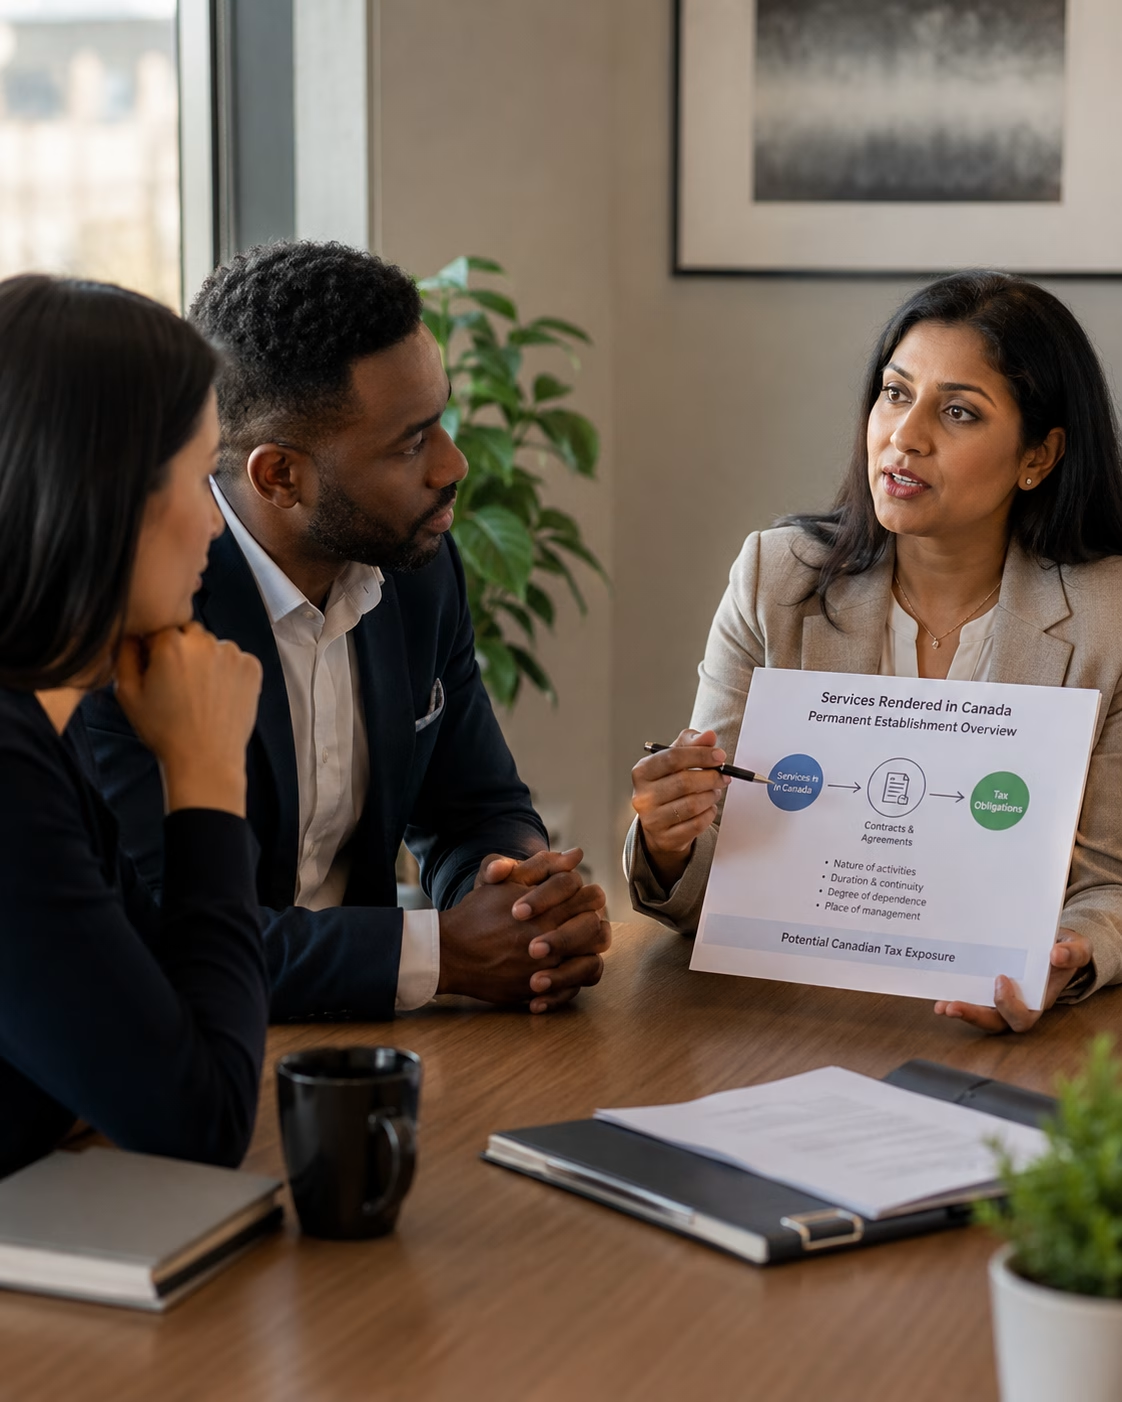
Withholding on Services Rendered in Canada
Payments made to a non-resident corporation for services rendered in Canada may be subject to withholding taxes. These withholdings can be applied to the amounts paid, even if the corporation’s final tax is lower or if a tax treaty allows for an exemption. Regularization may then occur through a return and appropriate request.
Foreign businesses must therefore monitor service contracts, invoices, the location of work performed, and relationships with Canadian clients. A lack of planning can create unexpected withholdings or cash flow difficulties.
Taxable Canadian Property and Asset Sales
A non-resident corporation selling taxable Canadian property, including certain real estate or interests related to Canadian assets, may have specific obligations. Depending on the property sold, a request for a compliance certificate may also be required. The transaction should be analyzed before closing to avoid significant withholdings or delays.
The T2 return may need to include gains, claimed exemptions, schedules, and necessary calculations. Impôts ici can assist you in coordinating this return with other steps related to the sale.
Satisfied Clients
Hours of Experience
In Tax Savings
T2 Declaration for Non-Resident Corporations
Accounting Organization and Documentation
Filing a T2 for a non-resident corporation requires clear accounting information. It is necessary to distinguish Canadian income, attributable expenses, contracts, withholdings, activity periods, currency conversions, and amounts already paid.
Foreign corporate documents may also be necessary to obtain a business number or support the file.
Good documentation allows the business to defend its position in case of questions from the Canada Revenue Agency. It also facilitates coordination with returns filed in the country of residence.
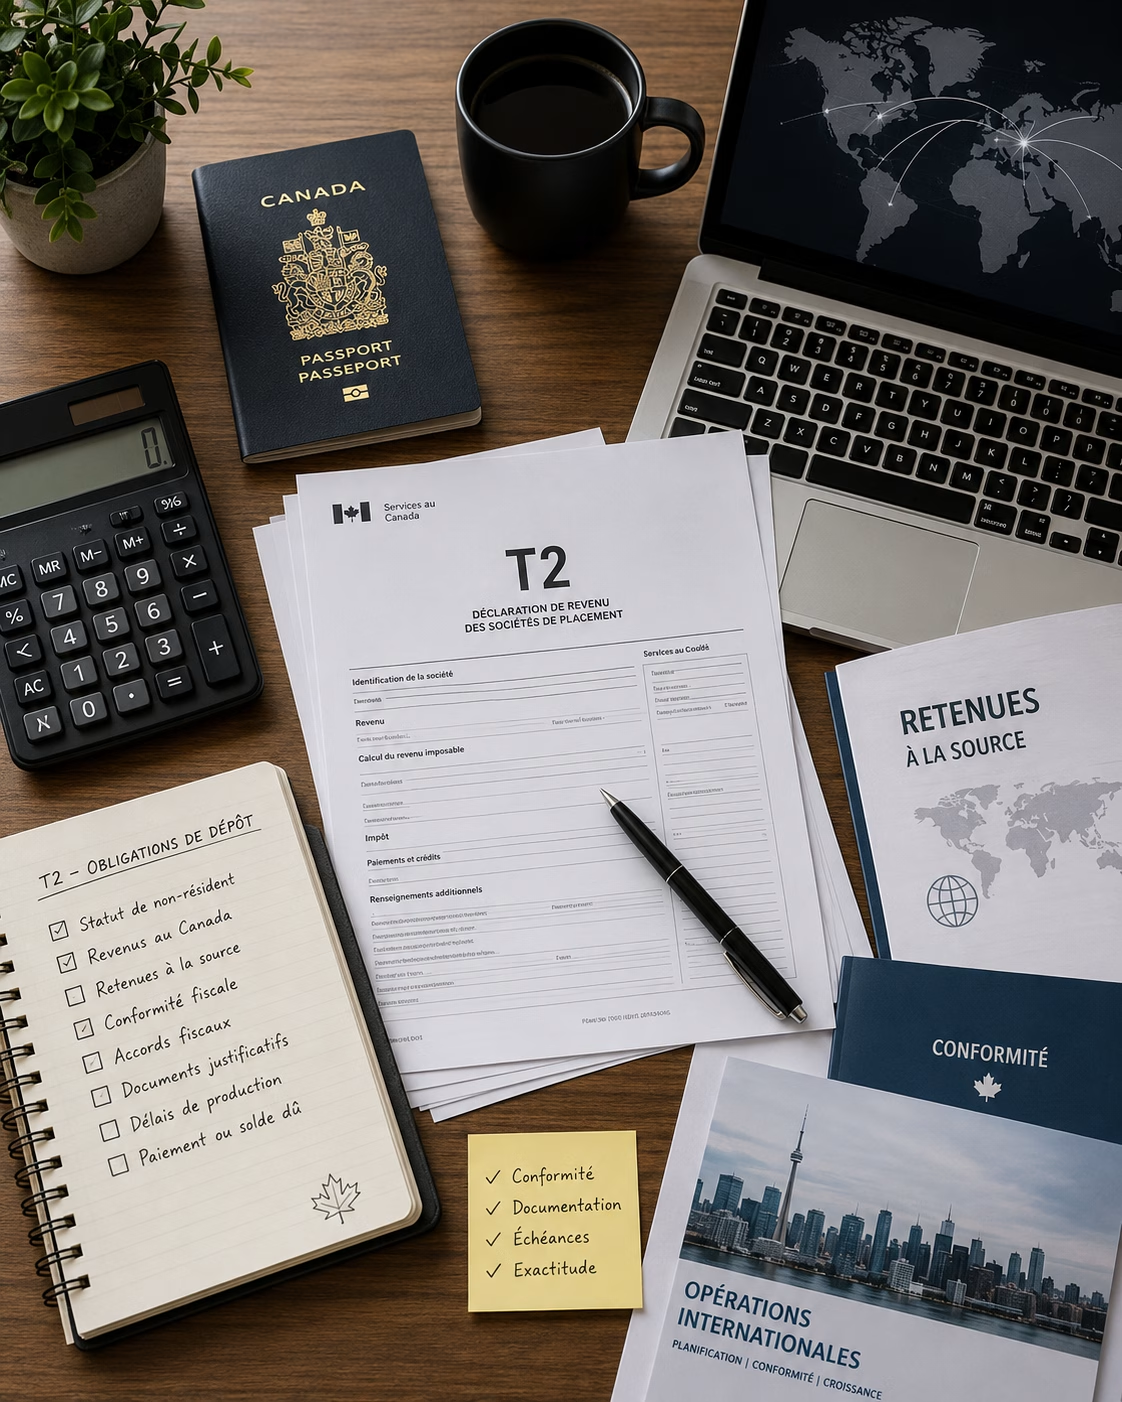
T2 Declaration for Non-Resident Corporations
Support for Foreign Corporations in Canada
The T2 return for a non-resident corporation should not be treated as an isolated formality. It is part of a broader strategy: presence in Canada, contracts, withholdings, tax treaties, investments, and potential expansion. Impôts ici supports you in determining your obligations, preparing the return, and structuring your compliance.
Whether your corporation sells in Canada, provides services, holds property, or prepares for establishment, our firm helps you secure your Canadian tax processes.
Before preparing a T2, it is useful to gather Canadian contracts, invoices, financial statements, withholdings incurred, proof of the corporation’s residency, organizational chart, activity periods, service execution locations, and foreign corporate documents. These elements help determine the extent of Canadian activity and the relevant schedules.
Impôts ici
A business near you, to help you!
Years of Experience Serving You.
Discover Us!
The T2 Declaration for Non-Resident Corporations with Impôts ici
Impôts ici can also analyze the corporation’s treaty position. Claiming an exemption based on a tax treaty requires solid documentation. This preparation facilitates filing, as well as defending the file if the CRA raises questions.
The T2 can also be used to recover or correctly apply certain withholdings already taken in Canada. Without a return, a foreign corporation may leave amounts immobilized or fail to recognize a position provided by treaty. A well-prepared filing thus addresses both compliance and cash flow.
This process is also important for groups wishing to test the Canadian market. Even a limited presence can create tax questions if contracts, employees, or services are tied to Canada.